Economic Insights
This collection of the latest updates and data from the systems integration industry explores leading indicators including the CEO Confidence Index, Purchasing Managers Index, and CSIA updates. We offer our own insights based on the information referenced and interactions with Exotek clients and the SI community.
CEO Confidence Index and PMI
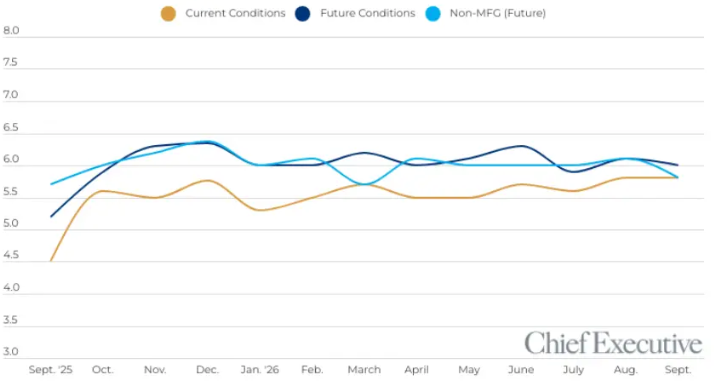
Manufacturing Holds Its Ground as CEO Confidence Stalls
Manufacturing CEO confidence held steady in September, although expectations for the year ahead softened slightly. Industrial manufacturers remained more optimistic than consumer-goods producers. Investment and hiring plans remained resilient despite growing pressure on profitability and working capital.
- Current Conditions: Held at 5.8/10, unchanged from August and matching the year’s highest reading.
- 12-Month Outlook: Eased to 6.0/10 from 6.1 in August.
- Revenue Outlook: 78% expect revenue to increase in 2026, compared with 77% in August.
- Profit Outlook: 65% expect profits to increase, down from 70% in August.
- Capital Investment: 51% plan to increase capital expenditures, essentially unchanged from 52% in August.
- Hiring Outlook: 49% plan to increase headcount, up from 45% in August.
- Key Risks: Rising operating costs, tariffs, geopolitical uncertainty, and liquidity pressures continue to weigh on manufacturers.
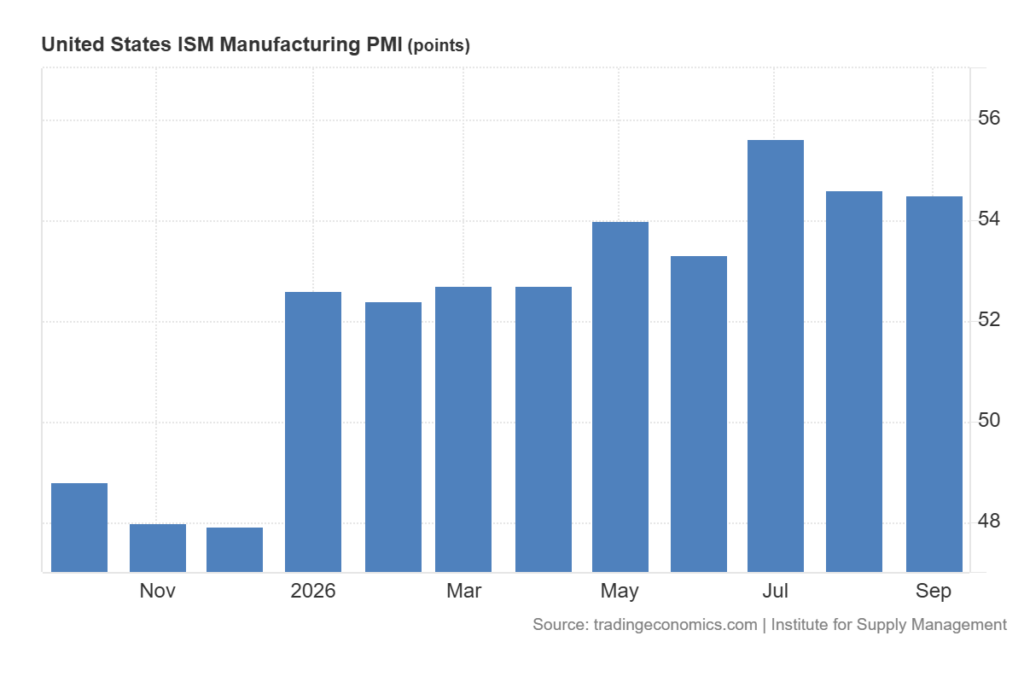
Manufacturing Expansion Continues as Orders Strengthen and Costs Rise
U.S. manufacturing expanded for the ninth consecutive month in September. New orders and backlogs strengthened, while production growth moderated. Rising input prices and continued delivery delays remain concerns.
- Manufacturing PMI: Registered 54.5%, essentially unchanged from 54.6% in August.
- New Orders: Increased to 55.3% from 53.7%, indicating faster demand growth.
- Production: Eased to 56.7% from 58.3%, marking the 11th consecutive month of expansion.
- Order Backlogs: Rose to 56.4% from 51.8%, signaling a growing pipeline of unfilled orders.
- Customer Inventories: Fell to 41.6% from 42.8%, remaining “too low”—a favorable indicator for future production.
- Employment: Increased to 52.7% from 51.2%, indicating faster workforce expansion.
- Supplier Deliveries: Registered 59.0% versus 59.3%; deliveries continued to slow, although slightly less than in August.
- Prices: Jumped to 77.9% from 71.1%, reflecting increased pressure from metals, tariffs, and petroleum-related costs.
- Industry Breadth: 12 of 18 industries reported growth, including five of the six largest manufacturing industries.
- Services PMI: Registered 54.9%, down slightly from 55.4% in August, marking the 27th consecutive month of expansion. Business activity and new orders continued to grow, although more slowly, while backlogs increased.
OUR KEY TAKEAWAYS
Industrial demand remains supportive of SI opportunities. Manufacturing expanded for a ninth consecutive month, with stronger new orders and backlogs. CEO confidence held steady, although the year-ahead outlook softened slightly. Together, these signals suggest continued demand with measured optimism.
Capital investment plans remain resilient. Just over half of manufacturing CEOs plan to increase capital spending, essentially unchanged from August. For system integrators, this supports a constructive project outlook, particularly where investments address clear operating needs.
Growing backlogs reinforce the need for productivity improvements. Orders strengthened while production growth moderated and customer inventories remained low. Our interpretation is that manufacturers have an incentive to improve throughput, reduce bottlenecks, and make better use of existing capacity.
Hiring growth complements the case for automation. Manufacturing employment expanded faster in September. Automation opportunities remain the strongest where they help manufacturers improve workforce productivity and overcome specific production constraints.
Costs and cash flow may drive greater project scrutiny. Input-price pressures intensified, while CEO profit expectations weakened and working-capital concerns persisted. We expect customers to emphasize demonstrable savings, manageable cash commitments, and clear payback.
Opportunities will vary by customer and end market. Industrial goods CEOs were more optimistic than consumer goods producers. System integrators should assess each customer’s demand, financial position, and investment priorities when evaluating opportunities.
Services-sector growth supports opportunities beyond manufacturing. Continued expansion in services, including utilities and transportation, provides a favorable demand signal for SIs serving these markets. However, rising costs and slower supplier deliveries reinforce the need to protect project margins and plan carefully around equipment lead times.
Non-Defense Capital Goods Excluding Aircraft (UNXANO) ROC Analysis
We have transitioned from tracking US Capital Goods New Orders (USCGNO) to UNXANO which provides a clearer indication of actual capital spending and better aligns with the focus of most system integrators.
Capital Investment Momentum Continues to Strengthen
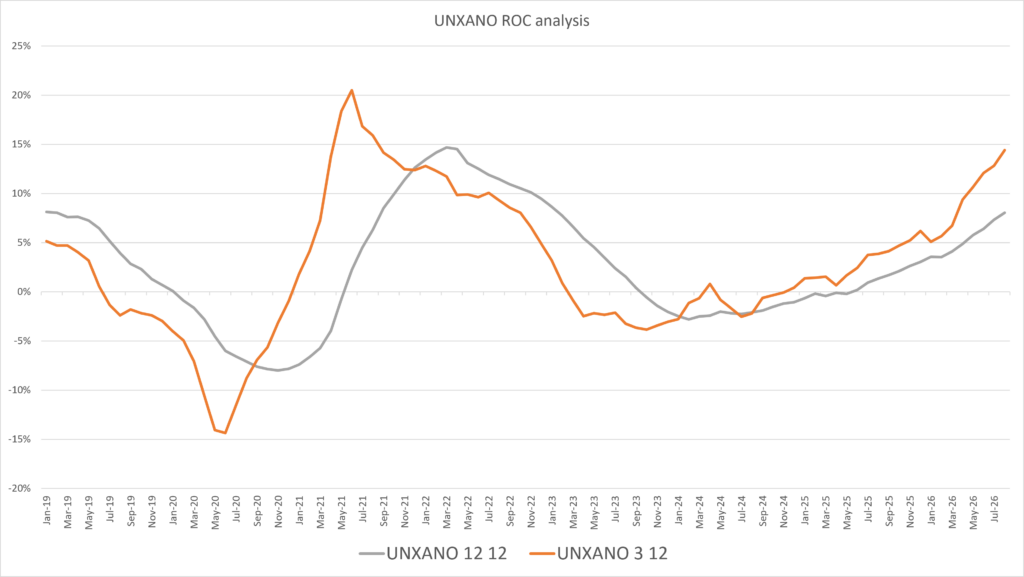
Orders for non-defense capital goods excluding aircraft (UNXANO) increased in August, while both short- and long-term growth rates strengthened. The three-month growth rate continued to exceed the 12-month rate, indicating sustained momentum in capital-equipment orders.
- Capital Goods Orders (UNXANO): Registered $85.4 billion in August, up from July’s revised $82.5 billion.
- Rolling 12-Month Total: Increased to $983.9 billion from $972.8 billion in July, reaching a new high in the supplied data.
- 12-Month Growth Rate: Improved to approximately +9%, up from +8% in July.
- 3-Month Growth Rate: Increased to approximately +14%, up from +13% in July.
- Rate-of-Change Outlook: Both growth rates strengthened, with short-term growth continuing to lead the longer-term trend, a favorable signal for future automation and system integration opportunities.
Manufacturers’ growing capital-equipment orders support a constructive outlook for SI project demand. These orders can create integration opportunities as equipment purchases move into implementation, although timing will vary by customer and project. SIs should use this signal to guide pipeline conversations and capacity planning, while continuing to assess customers’ funding, approval timelines, and expected returns.
Exotek Insights – UNXANO ROC Analysis
Exotek Insights – CSIA ROC Analysis
Exotek Insights – CSIA vs UNXANO Analysis
OUR KEY TAKEAWAYS
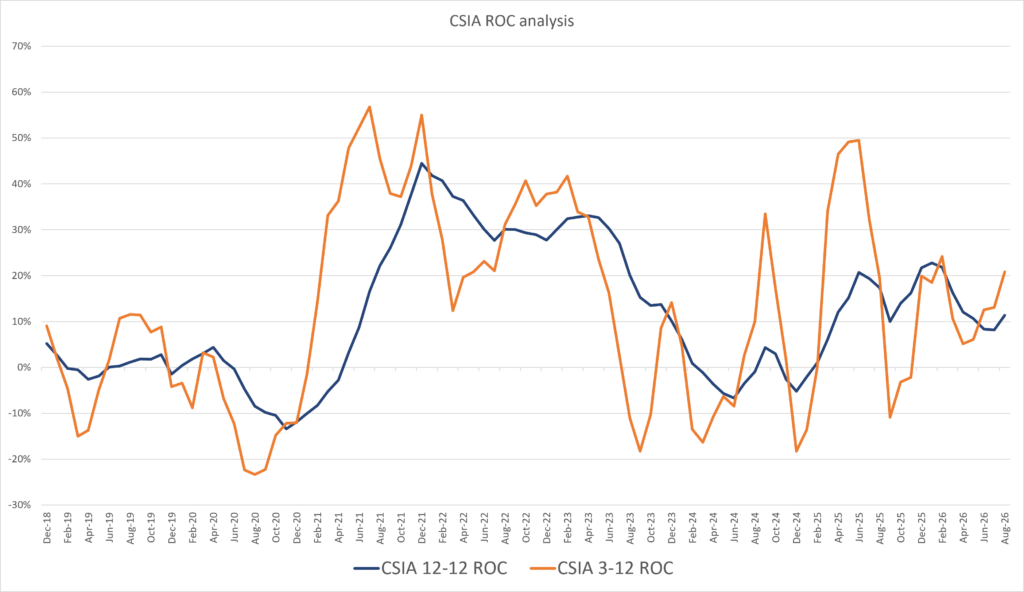
Capital investment and SI revenue growth are both strengthening. In August, UNXANO’s three-month growth rate reached approximately 14%, while CSIA’s increased to 21%. Their respective 12-month growth rates reached approximately 9% and 11%. Together, these indicators suggest a supportive capital-investment environment alongside improving SI revenue performance.
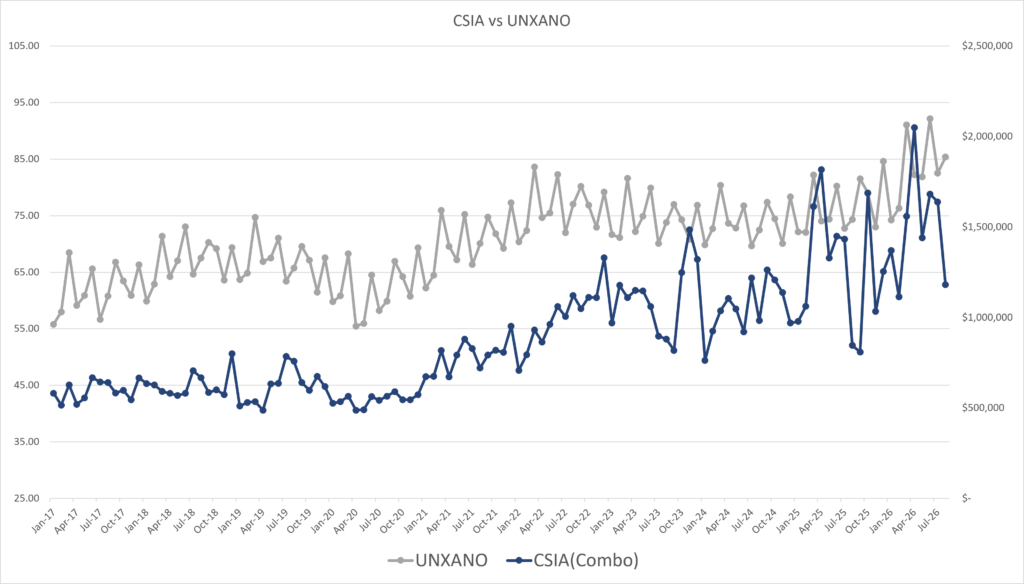
SI revenue growth accelerated in August. CSIA’s three-month growth rate increased from 13% to 21%, remaining above its 12-month rate. The combined revenue measure was approximately 40% higher than August 2025, bringing year-to-date growth through August to approximately 14%. These results support a strengthening trend, although monthly comparisons can fluctuate with project timing and survey participation.
Capital-equipment orders provide a favorable signal for future SI work. Industrial automation is a derived market: equipment investment can generate integration demand as projects move through approval, engineering, installation, and commissioning. Rising UNXANO orders and improving CSIA revenue are consistent with that relationship, although they do not establish a direct link between specific equipment purchases and SI revenue.
The outlook supports growth with disciplined planning. Strengthening capital-equipment orders, expanding manufacturing activity, resilient CEO investment plans, and improving SI revenue provide a constructive backdrop. SIs should pursue opportunities and assess delivery capacity while protecting margins and cash flow. Rising input costs, tariffs, supply constraints, and geopolitical uncertainty may still affect customer approvals and project schedules.
CSIA STATS ANALYSIS
OUR KEY TAKEAWAYS
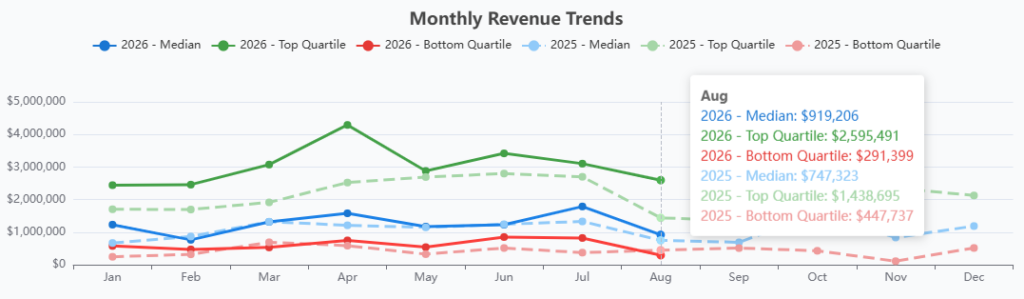
SI revenue growth remains strong overall, led by larger integrators. August’s upper-quartile revenue measure increased approximately 80% year over year to $2.60 million, while median revenue rose 23% to approximately $919,000. Given larger integrators’ substantial share of industry revenue, these gains support a positive overall market assessment. The lower-quartile measure declined 35%, indicating that favorable market conditions are not translating into growth for every firm.
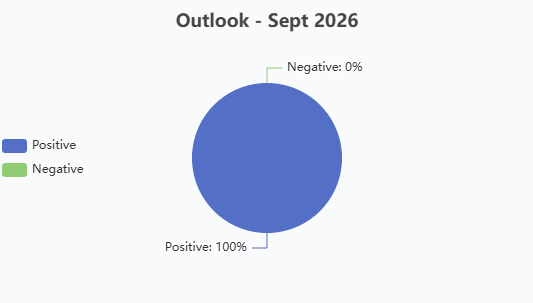
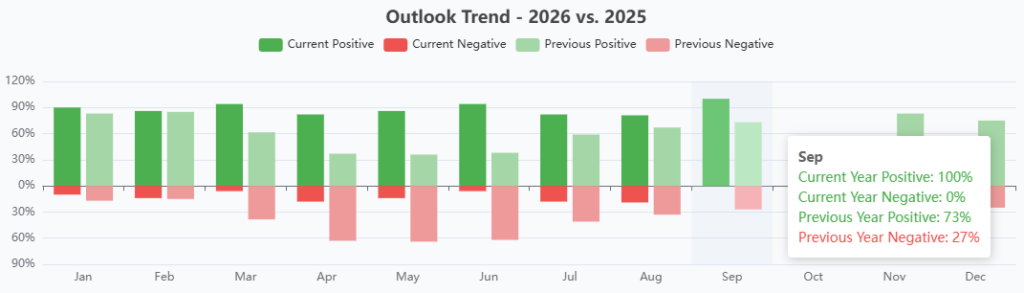
Business confidence strengthened considerably. 100% of September respondents reported a positive outlook, compared with 73% a year earlier. This signals strong confidence among participating firms, although it should not be interpreted as a guarantee of future orders or growth.
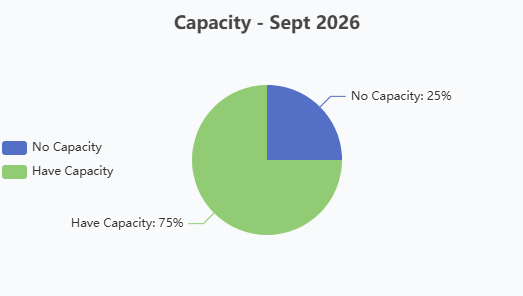
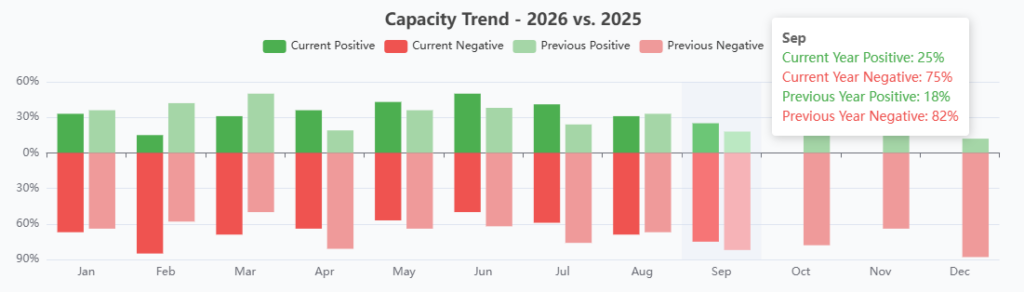
Capacity remains available to support additional work. 75% of September respondents reported available capacity, compared with 82% a year earlier. The share without available capacity increased from 18% to 25%, suggesting somewhat tighter delivery resources while most respondents still have room to take on projects.
Optimism creates an opportunity to convert available capacity into revenue. Strong confidence alongside available capacity suggests that many SIs anticipate opportunities beyond their current workload. Firms should focus on moving qualified opportunities through customer approvals and aligning staffing commitments with confirmed project schedules.
Plan around your own pipeline and operating results. Improving aggregate revenue and confidence support a constructive outlook, but the differing revenue results reinforce the importance of company-specific decisions. SIs should assess backlog quality, utilization, margins, and cash flow before expanding capacity or making significant hiring commitments.